

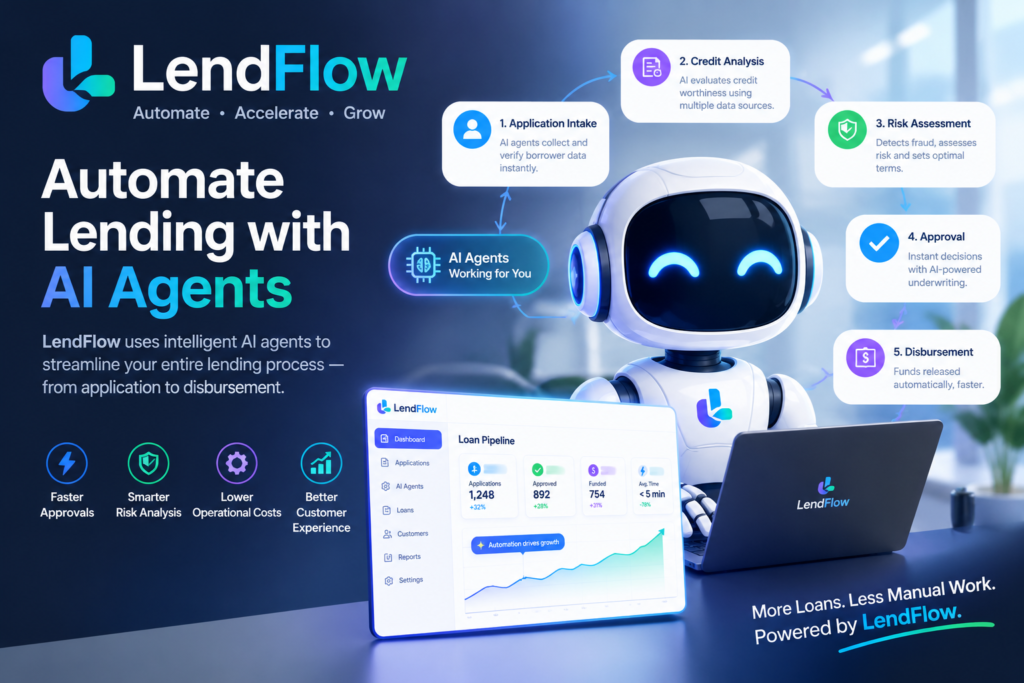
Lendflow Automate AI Agents Lending Automation
Lendflow Automate and AI Agents: A Practical Look at Lending Automation
Picture a small lending team on a Monday morning. The inbox has 140 unread emails, half of them borrowers asking “did you get my bank statements?” Someone is manually typing numbers from a PDF into a spreadsheet.The work is just repetitive, and it grows every time the business does.
That scene is why I got curious about Lendflow Automate. I should be upfront about how I approached it: I haven’t run a live lending desk on it. I read the public material, watched how the product is positioned, and compared it with what lending ops teams actually struggle with. So think of this as an informed outside look at what it does, where it could help, and how I’d test it before trusting it.
What Lendflow Automate Actually Is
Lendflow describes itself as embedded lending infrastructure for fintechs, SaaS platforms, and lenders. It offers APIs, orchestration tools, and AI automation to help companies launch and scale lending products while streamlining underwriting, compliance, and operations.
Lendflow Automate is the AI layer on top of that. It was announced in August 2025 as a suite of AI-powered agents meant to change how lending operations are run.
An “AI agent” here is not a magic robot lender. It’s software that handles one narrow job, such as answering a call, reading a document, or following up with a borrower. Lendflow’s own explanation is that agents differ from basic scripted automation because they can reason through exceptions, adapt to new data, and coordinate multi-step workflows.
One thing I noticed: the agent count isn’t consistent across Lendflow’s own pages. The launch announcement mentions more than 50 context-aware agents in production, while the August roundup post says over 30. That’s probably just timing or how they count, but it’s a good reminder to ask any vendor for specifics instead of trusting a headline number.
The Agents Worth Paying Attention To
Based on the public material, these are the areas that matter most for day-to-day operations.
Voice AI. Lendflow positions its voice agents for inbound and outbound calls, available around the clock, so borrowers aren’t stuck with missed calls or hold music. The part I’d look at closely is the handoff. Lendflow says its agents can transfer a customer to a human at any point in the conversation. That’s the right design. A voice agent that traps people is worse than no agent.
Document processing. This is the unglamorous one, and probably the most valuable. If your team spends hours retyping numbers, this is where you’d likely feel the difference first.
Chat and inbox automation. The suite includes an Inbox Automation Agent, and there’s an AI chatbot too. These handle the “did you get my documents?” flood.
Decisioning and collections support. Lendflow’s material covers credit decisioning automation and collections, where it says agents often deliver the most dramatic results. I’d treat that as a claim to verify with your own numbers, not a promise.
A Realistic Example
Here’s a composite scenario (not a customer story) of how this might play out for a small business lender.
A borrower applies on Friday evening. Without automation, nothing happens until Monday. With an agent setup, the borrower gets a text asking for missing bank statements, uploads them, and the document agent pulls out the key figures. By Monday morning, the underwriter opens a file that’s already organized instead of a pile of PDFs.
The humans still make the decisions. That’s the version of automation I find believable.
Step by Step
If I were running ops at a lender and wanted to try this, here’s the order I’d follow.
Step 1: Pick one painful, boring task.
Don’t automate “the whole pipeline.” Choose the single task that eats the most hours. For most teams that’s document collection or borrower follow-ups.
Step 2: Write down how that task works today.
Who does it, how long it takes, how often it goes wrong. You need a baseline, or you’ll never know whether the agent helped.
Step 3: Ask how it connects to your systems.
Lendflow says it triggers specialized agents based on workflow events and returns standardized outputs that feed into existing systems. Ask for a walkthrough of how that works with your actual loan management system, not a generic demo.
Step 4: Run a small pilot.
Use a limited batch of applications or one borrower segment. Lendflow says voice AI can be set up in just a few days, which makes a small pilot realistic. Fast setup is also a reason to be careful. Don’t let speed push you past testing.
Step 5: Keep a human reviewing the output.
Check extracted numbers against the original documents for the first few weeks. Track errors, not just time saved.
Step 6: Listen to the calls and read the messages.
Tone matters in lending. A borrower who’s stressed about money can be put off by one clumsy automated sentence.
Step 7: Measure against your baseline, then expand.
Only widen the rollout when the pilot numbers justify it. Lendflow Automate AI Agents Lending Automation
Questions to Ask Before You Sign Anything
A few things I’d ask any vendor in this space, Lendflow included:
- Where does the AI stop and a human take over?
- How are extraction errors caught before they affect a decision?
- Where is borrower data stored, and who can access it?
- How does the system support compliance requirements in the regions you lend in?
- Can I see results from a business similar to mine, not just a headline stat?
These aren’t criticisms of Lendflow. They’re questions every lender should ask about any AI tool touching financial decisions.
Mistakes to Avoid
Believing the biggest number on the page.
Claims like decisions going “from days to minutes” appear in coverage of Lendflow. One outside write-up notes that this is based on Lendflow’s own public claims. Your results depend on your data, your process, and your risk rules.
Automating a broken process.
If your workflow is confusing for humans, an AI agent will just be confused faster. Clean up the process first.
Removing humans too early.
One analysis of the product puts it well: automation is a tool, not a substitute, for relationship-driven lending. I agree. Borrowers with unusual situations still need a person.
Ignoring fair lending and compliance.
Anything that influences credit decisions needs oversight.
Skipping the baseline.
Without before-and-after numbers, you’ll end up arguing about whether it “feels” faster. Lendflow Automate AI Agents Lending Automation
Who It Seems Best Suited For
From what I’ve read, it makes the most sense for fintechs, SaaS platforms adding lending to their products, and lenders with high application volume and a small ops team. Lendflow’s material says agents let operations scale during peak periods without proportional hiring.
If you’re a tiny lender processing a handful of loans a month, the setup effort may not pay off yet. A spreadsheet and a good checklist might be enough.
Final Thoughts
Lendflow Automate fits a real need. Lending ops are full of repetitive, rules-based tasks that burn out good people, and AI agents are well suited to exactly that kind of work.
But the best way to think about any lending automation tool is as a very fast junior assistant. It’s great at the repetitive parts, it needs supervision, and it should never be the last line of defense on a decision that affects someone’s finances. If you’re curious, start with one workflow, measure honestly, and keep a human in the loop. Lendflow Automate AI Agents Lending Automation
Leave a Reply